Market Correction?

Last Monday, the U.S. markets dropped roughly 1% of their value (as measured by the S&P 500 index), and Europe and Asia were down by similar amounts the following day. The market then fell 2.1% on Friday in a sickening lurch. Today the S&P 500 fell another 0.5%. This combination was enough to cause pundits and investors to ask whether we are now in the early stages of a bear market or, indeed, if the past almost-five years should be considered an interim market rally inside of a longer-term bear market.

The answer, of course, is that nobody knows–not the brainiac Fed economists, not the fund managers and certainly not the pundits. A Wall Street Journal article noted that most of the sellers on Friday were short-term investors who were involved in program trading, selling baskets of stocks to protect themselves from short-term losses. Roughly translated, that means that a bunch of professional traders panicked when they learned that Chinese economic growth is slowing down on top of worries that the Fed is buying bonds at a somewhat less furious rate ($75 billion a month vs. $85 billion) than it was last year.

What we DO know is that it is often a mistake to panic sell into market downturns, which happen more frequently than most of us realize. A lot of people might be surprised to know that in the Summer of 2011, the markets had pulled back by almost 20%–twice the traditional definition of a market correction–only to come roaring back and reward patient investors. There were corrections in the Spring of 2010 (16%) and the Spring of 2012 (10%), but almost nobody remembers these sizable bumps on the way to new market highs. Indeed, most of us look back fondly at the time since March of 2009 as one long largely-uninterrupted bull market.

Bigger picture, since 1945, the market has experienced 27 corrections of 10% or more, and 12 bear markets where U.S. equities lost at least 20% of their value. The average decline was 13.3% over the course of 71 trading days. Perhaps the only statistic that really matters is that after every one of these pullbacks, the markets returned to record new highs. The turnarounds were always an unexpected surprise to most investors.

We may get a full 10% correction or even a full bearish period out of these negative trading days, and then again we may not. But history suggests an important lesson: if we DO get a correction or a bear market, we may not remember it a few years later if the markets recover as they always have in the past. The people who lose money in the long term are not those who endure a painful market downturn, but those who panic and sell when the market turns down. The facts are that the market is overdue for a reasonable correction after the torrid and virtually uninterrupted run up we’ve had since late 2012.

Instead of panic selling into the market downturn, you may choose to lighten up your equity weighting or re-balance some of your equity weight into other asset classes. After a long winning run, it never hurts to take some profits off the table, trim back your winners and leave the proceeds in cash to invest when the downturn ends. There are various inverse funds and other options available to partially hedge your portfolio if the uncertainty keeps you up at night. After a few days of selling, there’s usually a rally around the corner to counterbalance the weight of the selling and that’s a more opportune time to lighten up. None of this is a recommendation–they’re just some ideas to consider.

For our clients, we have raised and maintained a healthy level of cash and have used hedging to reduce our overall portfolio risk. If the correction becomes prolonged, we’ll do more of the same and await the next opportunities to re-invest. No one says that you have to stay 100% invested at all times.

If you have any questions or would like to speak to us about your portfolio needs or any financial planning matters, we’re here to help. We are a fee-only financial planning firm that always puts your interests first.
Fee-Only Financial Advisers Who Aren’t

Today’s (Saturday September 21, 2013) Wall Street Journal contains an article entitled ” ‘Fee-Only’ Financial Advisers Who Don’t Charge Fees Alone” written by award-winning writer Jason Zweig, better known as “The Intelligent Investor.” Jason acts as beacon to guide investors towards the better practices of saving and investing and warns them of the tricks and traps.

In this article, Jason points out that “You might think a “fee-only” financial adviser will never charge you commissions or other sales charges that could induce him to favor selling you something that is better for him than for you. Think again.”

Through his research, he found that many advisors who hold themselves out as “fee-only” indeed earn commissions, kickbacks, trails or other hidden compensation even though they might not sell you a product that generates one. He found that numerous advisors (661) that were Certified Financial Planners (TM) and worked for large Wall Street brokerage firms such as Morgan Stanley, UBS, RBC, Wells Fargo, J.P. Morgan Chase, Bank of America Merrill Lynch, Raymond James and Ameriprise Financial also listed themselves as fee-only advisors on the CFP (r) website. By definition, based on the nature of the firms that they work for, they cannot designate themselves as fee-only advisors or planners.

Many people also confuse fee-only with fee-based. They are definitely not the same. Fee-based means that the advisor can earn both fees for services as well as other commissions or kickbacks for selling investment, insurance or other financial products.

NAPFA, the National Association of Personal Financial Advisors (the de facto fee-only organization of planners and advisors found at napfa.org), the Financial Planning Association and the Certified Financial Planner board of standards are currently working on more clearly defining the “fee-only” standard and urging members to update their profiles and re-assert that they meet the more clearly-defined standard. I applaud this effort.

I wish to reassure our clients, prospects and friends that our firm, YDream Financial Services, takes a very serious and crystal clear stance on meeting the fee-only definition. Fee-only planners, like us, are compensated solely by fees paid by our clients and we do not accept commissions or compensation of any kind from any source. We also don’t earn any money or consideration from trails, referrals or markups. We have zero incentive to recommend any financial products and don’t accept anything (except perhaps trinkets from wholesalers or fund companies worth $5 or less handed out at conferences) that influences our recommendations. Our custodian, Charles Schwab does not reimburse or compensate us for any trade commissions or for the use of any particular financial products that they offer.

As a fiduciary, we take our responsibility to put your interests first and we endeavor do that in every recommendation or transaction that we initiate on your behalf. Finally, any conflicts of interest that our compensation approach might present are clearly discussed and disclosed with our clients and prospects prior to implementing the recommendation or moving forward with the engagement.

You can find the Wall Street Journal Article here http://goo.gl/23Oy3B. It’s worth the short read. If the link requires a log in or subscription to the Wall Street Journal Online, I suggest typing the title of the article above into your favorite search engine then click on the search hit that it finds.

Your Returns Versus the Market

One of the most misleading statistics in the financial world is the return data we are routinely given by the financial media, telling us how much investors made in the markets and in individual stocks or mutual funds over some time period.  In fact, your returns are almost guaranteed to be different from whatever the markets and the funds you’ve invested in have gotten.

How is this possible?  Start with cash flows.  We are told that the S&P 500 has delivered a compounded return of about 7.8% from 1992 through 2011, which sounds pretty positive until you realize that this return would only be available to somebody who invested all his or her money at the beginning of 1992 and didn’t move that money around at all for the next twenty years.  If you invested systematically, the same amount every month, as most of us do, then you would have earned a 3.2% compounded return.  Why?  A lot of your money would have been exposed to the 2008 downturn, and not much of it would have enjoyed the dramatic run-up in stocks from 1992 to 2000.

In addition, there is the difference–only now getting attention from analysts–between investor returns and investment returns.  Human nature drives investors to sell their stocks and move to the sidelines after their portfolios have been hammered–which is often the worst possible time to sell.  And it drives people to start increasing their equity allocations toward the peak of bull markets when they perceive that everybody else is getting rich.  That means less of their money tends to be exposed to stocks when the market turns from bearish to bullish, and more is exposed when markets switch from bullish to bearish.

Understand also that owning a diversified portfolio means that only a portion of your investments are exposed to stocks. Assets such as cash, bonds, real estate, commodities and other non-stock investments all have returns that are inherently different than stocks, making overall portfolio return comparisons an “apples to oranges” one.

This would be bad enough, but people also switch their mutual fund and stock holdings.  When a great fund hits a rough patch, there’s a tendency to sell that dog and buy a fund that whose recent returns have been scorching hot.  Many times the underperforming fund will reverse course, while the hot fund will cool off.  The Morningstar organization now calculates, for every fund it follows, the difference between the returns of the mutual fund and the average returns of the investors in fund, and the differences can be astonishing.  Overall, according to Morningstar statistics and an annual report compiled by the Dalbar organization, investor returns have historically been about half of what the markets and funds are reporting.

And then there’s the tax bite.  Some mutual funds invest more tax-efficiently than others, and generate less ordinary income.  Beyond that, if a fund is sitting on significant losses when you invest, you get to ride out its gains without having the tax impact distributed to your 1040.  If the fund is sitting on large gains when you buy in, you could find yourself paying taxes on gains even if the fund loses money.

Sources:

http://www.forbes.com/sites/financialfinesse/2012/06/20/why-your-investment-returns-could-be-lower-than-you-think/

http://www.thesunsfinancialdiary.com/investing/understanding-ms-total-return-and-investor-return/

http://corporate.morningstar.com/cf/documents/MethodologyDocuments/FactSheets/InvestorReturns.pdf

My thanks to Inside Information publisher Bob Veres for his contribution to this post.

Handle Asset Location With Care

An old question has become new again.  You have tax-deferred accounts like IRAs and Roth IRAs, and you have accounts that pay taxes every year on the income they receive.  Where do you put different types of assets? 

The answer is that you want to put the most tax-inefficient investments inside the tax-deferred accounts.  The most notoriously tax-inefficient investments, historically, have been bond funds, commodities futures funds and real estate investment trusts (REITs), which all generate ordinary income that can be taxed at 39.6% plus the 3.8% Medicare tax for higher-income taxpayers.  The Roth IRA, which shelters all future returns from taxes of any sort, can be a great place for mutual funds that invest in small cap stocks, since they tend to have high turnover and historically have provided the highest gains.  

In taxable accounts, you might put growth stocks which, if you hold them for more than a year, will have their price appreciation taxed at a maximum rate of 20% (or 23.8% with the Medicare surtax).  Of course, you can choose to hold individual securities for much longer periods, which gives you tax deferral on its own–and, if the stocks are held until death, the heirs get a step-up in basis, which basically means any rise in value is never taxed.  Municipal bonds which qualify for an exemption from federal taxes are also good candidates for the taxable portion of your investment accounts. 

What makes this debate new again?   Higher ordinary income tax rates, and potentially higher capital gains tax rates (up from 15% to 23.8% for tax filers who have to pay the new Medicare surtax) have introduced some gray areas, as have the historically low rates on bonds.  When bonds were delivering upwards of 10% on the investment dollar, putting them in an IRA was a no-brainer.  But what if you’re cautious about rising rates, and you’ve shortened maturities in a yield-starved market, so your return is closer to 1%?   Suddenly, these funds are no longer a huge tax concern. 

At the same time, REITs offer tax benefits like depreciation, which becomes more valuable at higher ordinary income rates.  And persons in retirement may see their tax rates fall from above 39% down to 15%, which decreases the benefits of astute asset location, and might raise the value of rebalancing each year across all accounts. 

Another consideration for retirees is the mandatory withdrawals they have to take from their IRA account after they reach age 70 1/2.  If the IRA is holding all the income-generating investments, then systematically liquidating those holdings means creating a higher exposure to stocks and a generally more volatile portfolio as you age–which may be the opposite of what is desired.

Saving taxes through asset location strategies is one of those rare opportunities to get additional dollars without taking additional risk–but a mindless focus on taxes without looking at the bigger picture can result in unintended consequences.  The rules of thumb need to be informed by your tax bracket and other aspects of your individual circumstances–with an eye on the ever-changing tax and interest rates that Congress and the markets throw at us. 

Source:

http://www.financial-planning.com/fp_issues/43_8/asset-allocation-rules-2685905-1.html?zkPrintable=1&nopagination=1


 Many thanks to Bob Veres, publisher of Inside Information for his help writing this blog post.


The Rollercoaster Effect

There are two kinds of investor in this world.  One type pays close attention to the daily (and sometimes hourly) flood of information, looking for a reason (any reason) to jump in or out of the markets.  The other kind of investor is in for the long haul, and recognizes that the markets are going to experience dips and turns.  If these people are particularly wise, they know that the dips and turns are the best friend of the steady, long-term investor, because as you put money into the markets, as you re-balance your portfolio, you gain a little extra return from the occasional opportunities to buy at bargain prices.

Last week, the investment markets made an unusually sharp turn on the roller coaster, and showed us once again the sometimes-comical fallacy of quick trading.  See if you can follow the logic of the events that led to last week’s selloff.  Federal Reserve Board Chairman Ben Bernanke and the Federal Open Market Committee issued a statement saying that the U.S. economy is improving faster than the Fed’s economists expected.  Therefore (the statement went on to say) if there was continued improvement, the Fed would scale back its QE3 (quantitative easing) program of buying Treasury and mortgage-backed securities on the open market, and ease back on stimulating the economy and keeping interest rates low.

Everybody knows that the Fed will eventually have to phase out its QE3 market interventions, and that this would be based on the strength of the economy, so this announcement should not have stunned the investing public.  Nothing in the statement suggested that the Fed had any immediate plans to stop buying altogether; only ease it back as it became less necessary.  The statement said that this hypothetical easing might possibly take place as early as this Fall, and only if the unemployment rate falls faster than expected.  At the same time, the Fed’s economists issued an economic forecast that was more optimistic than the previous one.

The result?  There was panic in the streets–or, at least, on Wall Street, where this bullish economic report seems to have caused the S&P 500 to lose 1.4% of its valueon Wednesday and another 2.5% on Thursday.

In addition–and here’s where it gets a little weird–stocks also fell sharply in Shanghai and across Europe, and oil futures fell dramatically.  How, exactly, are these investments impacted by QE3?

The only explanation for last week’s panic selloff is that thousands of media junkie investors must have listened to “we plan to ease back on QE3 when we believe the economy is back on its feet again,” and heard: “the Fed is about to end its QE3 stimulus!”

It’s possible that the investors who sold everything they owned on Wednesday  throughFriday will pile back in this week, but it’s just as likely that the panic will feed on itself for a while until sanity is restored.  If stocks were valued daily based on pure logic, on the real underlying value of the enterprises they represent, then the trajectory of the markets would be a long smooth upward slope for decades, as businesses, in aggregate, expanded, moved into new markets, and slowly, over time, boosted sales and profits.  The roller-coaster effect that we actually experience is created by the emotions of the market participants, who value their stocks at one price on Wednesday, and very different prices on Thursday and Friday.

The long-term investor has to ask: did any individual company in my investment portfolio become suddenly less valuable in two days?  Did ALL of their enterprise values in aggregate become less valuable within 48 hours–and at the same time, did Chinese and European stocks and oil also suddenly become less valuable?  Phrased this way, the only possible answer is: no.  And if that’s your answer, then you have to assume that eventually, people will eventually be willing to pay the real underlying value of the stocks in the market, and the last couple of days will be just one more exciting example of meaningless white noise.

With all that said, it’s prudent to be cautious about going “all in” on this pullback in the market and to perhaps take some hard-earned partial profits on positions you’ve been holding. In our clients’ portfolios, we’ve upped our hedges and taken partial profits on short-term positions, but are still holding the majority of our equities and bonds.

With the action in the markets last week, we officially have the beginnings of a downtrend, but that can be very short-lived in this QE environment, so we remain on our toes. Be sure to consult with your advisor if you’re uncomfortable with your holdings or have trouble sleeping at night because of your positions. Nothing in this message should be construed as investment advice or suggestions to buy or sell any security.

If you have any questions or comments, please don’t hesitate to contact us or post them here. We are a fee-only fiduciary financial planning and investment advisory firm that always puts your interests first.

Have a great week!

Sam

Sam H. Fawaz CFP™, CPA
Registered Investment Adivsor Representative
NAPFA Registered Fee-only Advisor
Financial Planning Asssociation Member
(734) 447-5305
(615) 395-2010
http://www.ydfs.com

TheMoneyGeek thanks Bob Veres, publisher of Inside Information for his help with writing this guest post.

Investing by Population

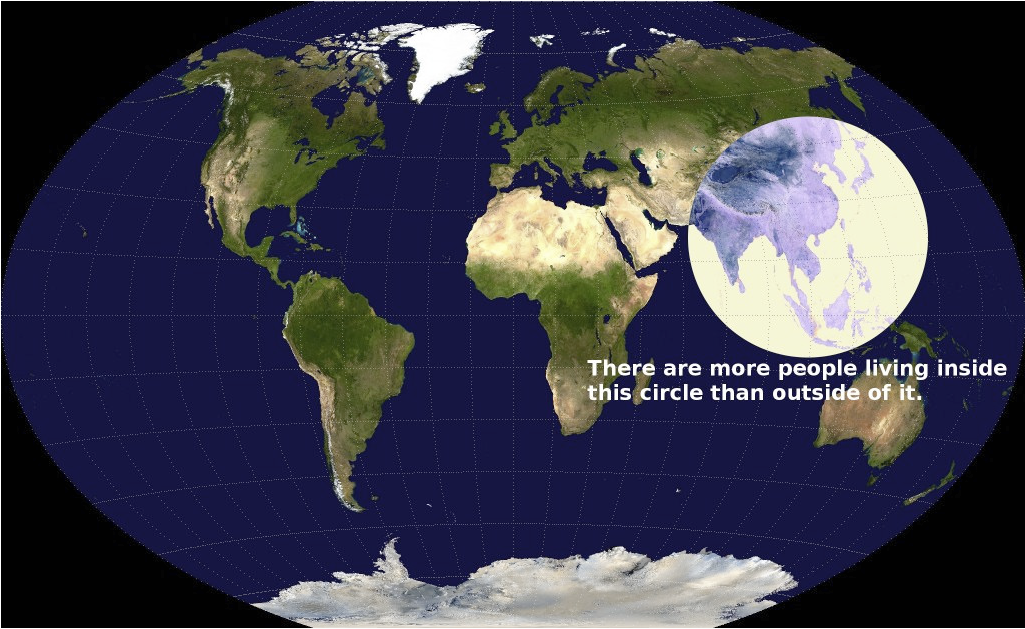
The map you see below has been widely circulated among professional investors, and it tells an astonishing story.  The circle encloses less than an eighth of the world’s total land mass, but it includes more than half of the world’s population.  Within that circle are the world’s two most populous nations: China, with 1.35 billion people and India with 1.22 billion, plus countries that rank 4th in population (Indonesia, with 251 million), 8th (Bangladesh, with 164 million), 10th (Japan, with 127 million), 12th (Philippines, with 106 million), 13th (Vietnam, with 92 million), 20th (Thailand, with 67 million), 25th and 26th (Burma and South Korea, both with around 50 million).  Also in the circle: Nepal, Malaysia, North Korea, Taiwan, Sri Lanka, Cambodia, Laos, Mongolia and Bhutan.

Add them up and you have 3.64 billion total citizens, or roughly 51.4% of the world’s people.

CA - 2013-5-12 - World Map

So the immediate question is: why isn’t my investment portfolio 50% invested in this region of the world?  Why isn’t my portfolio weighted by population?

The answer is simple.  While this circle represents the world’s center of gravity as measured by people, it also surrounds some of the least efficient places to deploy your investment resources.  Take China, for example, where the same company’s shares trading on the Hong Kong stock exchange routinely cost two or three times more than shares trading in Shanghai, where Chinese residents buy and sell their stocks.  Both shares carry identical claims on assets and profits.

Why the difference?  Chinese residents invest through so-called A-shares, which most foreign buyers are forbidden to trade in.  The rest of us buy B shares trading in Shanghai or Shenzhen, or H shares traded in Hong Kong, or red chips if the companies are state-owned, or P chips if the Chinese company is incorporated outside of the mainland, or N shares for certain Chinese companies listed on the U.S. trading floors.  These other share classes share one thing in common: they trade at higher multiples than the relative bargains offered to Chinese citizens.  China has granted several foreign firms and investment groups permission to own limited amounts of A shares, but it’s not easy to know, from the outside, which firms have an inside track.

Another problem with investing in China is transparency–or, more precisely, the lack of it.  U.S.-based public companies are required to disclose their financials in great detail, and large accounting firms are required to audit and sign off on the accuracy of those statements.  In China, accounting standards run from lax to nonexistent, and the Chinese government can forbid foreign access to the books and records of any company on the theory that this might reveal “state secrets.”

Okay, so what about India?  Here again, the government forbids non-Indian investors to buy shares of publicly-traded companies. Only six of the 30 companies listed in the BSE SENSEX index–the Indian equivalent of the S&P 500–allow shares to trade on the U.S. exchanges.  A few Indian-focused exchange traded funds are allowed to buy shares.

Indonesia’s stock exchange, meanwhile, could be charitably described as “undeveloped.”  Currently, it facilitates trading in just 462 listed companies, which have a combined market value of $462.78 billion–almost exactly the current market capitalization of Apple Computer.  Trading activity on the Jakarta stock exchange makes up less than one tenth of one percent of the global investment flow.

Of course, the Japanese stock market is large and robust, but investors in Japanese stocks have been less-than-thrilled by their performance since 1991.  The Nikkei 225 Stock Market Index peaked at just under 40,000 22 years ago, and now is worth about 12,500.

There is no question that eventually the people living inside of this interesting circle will start punching their weight in the global economy and provide thriving investment opportunities that will conform to more stringent world standards.  For now, a prudent investor will avoid investing by population.  You should have some money in the emerging economies and watch closely the new developments in Japan, where the prime minister may be shaking the economy out of a decades-long slump.  There may come a time when it will be wise to put more than half of your investments into eastern Asia, but that time hasn’t quite arrived yet.

Sources:

http://www.washingtonpost.com/blogs/worldviews/wp/2013/05/07/map-more-than-half-of-humanity-lives-within-this-circle/

http://www.forecast-chart.com/historical-nikkei-225.html

http://www.indexuniverse.com/sections/white-papers/15113-the-complete-guide-to-chinese-share-classes.html?fullart=1&start=5

http://seekingalpha.com/article/829631-how-can-americans-invest-in-indian-stocks

http://en.wikipedia.org/wiki/Jakarta_Stock_Exchange

http://en.wikipedia.org/wiki/List_of_stock_exchanges

http://www.advfn.com/nyse/newyorkstockexchange.asp

http://en.wikipedia.org/wiki/Indonesia_Stock_Exchange

http://www.usnews.com/opinion/blogs/economic-intelligence/2013/01/11/the-us-must-challenge-chinas-accounting-standards

TheMoneyGeek thanks Bob Veres, publisher of Inside Information for this guest post.

Bond Market Outlook: Points to Ponder

During the past decade, many long-term fundamentals of investing have been turned upside down and one example is the performance of U.S. stocks compared with bonds. Over longer time periods, such as 20 or 30 years, stocks exhibited higher average annual returns along with greater volatility.Bonds, in contrast, presented lower long-term returns along with fewer ups and downs.

But the 10-year period ending December 31, 2011, has shown the opposite, with the average annual return of investment-grade bonds exceeding stocks by a margin of 5.8% compared with 2.9%.1 No one knows for sure whether the recent outperformance of bonds will continue, but events currently present in the U.S. economy are causing observers to question the outlook in the years ahead.

Interest Rates The Federal Reserve has maintained the federal funds rate between 0.0% and 0.25% with the goal of stimulating the economy. Given how low short-term interest rates are, it is likely that they will turn upward at some point, which would present challenges for bondholders. Historically, higher interest rates have caused the prices of existing bonds to fall as investors have pursued newly issued bonds paying higher rates. This scenario presents the potential for losses for existing bondholders.

Inflation During 2011, inflation averaged 3.2%, close to the historical average of 2.9%.But if inflation were to increase even higher, an investor would lose money on a bond with a yield lower than the rate of inflation. Some observers believe that if the U.S. economy begins generating stronger growth, inflation could once again spike upward.

Federal Spending Sizeable federal deficits are almost old news as the government looks for ways to stimulate the country’s economic engines. While economic growth is a laudable objective, outsized federal spending may impact the financial markets. If the federal government is forced to pay higher interest rates to entice investors to fund the debt, this action could lead to higher interest rates on other types of bonds as well in response to investor demand.

Bonds can help investors balance a portfolio weighted to stock funds or other assets. When making decisions about investments, it is important to weigh both the benefits and the risks associated with bonds and any other assets that you own.

Source/Disclaimer:

1Sources: Standard & Poor’s; Barclays Capital. Stocks are represented by the Standard & Poor’s 500 Index, bonds by the Barclays Aggregate Bond Index, volatility by standard deviation. Results are for the 30-year period ending December 31, 2011. You cannot invest directly in an index. Past performance does not guarantee future results. Investing in stocks involves risks, including loss of principal. Bonds are subject to market and interest rate risk if sold prior to maturity. Bond values will decline as interest rates rise and are subject to availability and change in price.

2Source: U.S. Bureau of Labor Statistics. Inflation is represented by the Consumer Price Index. Historical average is for the period between 1926 and 2011.

June 2012 — This column is provided through the Financial Planning Association, the membership organization for the financial planning community, and is brought to you by YDream Financial Services,a local member of FPA.

What’s Going on With The Markets? 3rd Quarter 2011

The headline on today’s Wall Street Journal says it all: “Stocks Log Worst Quarter Since ’09”, referring of course to the first quarter of 2009 before the start of the (current?) bull market run. Even quarter-end “window dressing”, where fund managers buy up the best performing stocks to make their holdings look good to shareholders and boost their chances of quarterly performance bonuses didn’t help at all. September 30th ended the day, week, month and quarter-end at an ominous level.
 
The shocks to the markets continue to come from the Eurozone debt crisis, worries of another recession starting, the Chinese economy slowing, and now, corporate earnings results for the third quarter coming in below estimates. Forward guidance, that is, how companies estimate their upcoming earnings, are expected to be pulled down a bit. With economic data continuing to soften or come in worse than expected, evidence is mounting that the economy continues to slow down, but not contract. Contraction for two straight quarters is the textbook definition of the start of a recession.
 
My most reliable source for forecasting a recession comes from the Economic Cycle Research Institute (ECRI). In the past, they have been spot on in identifying the conditions that precede the onset of a recession.  This week, although not confirming the start of a recession, the ECRI did confirm that evidence of a recession is spreading like wildfire and one would be almost impossible to avoid given current conditions.  Consumer confidence is at or near an all-time low due partly because of the whole debt ceiling debacle and political gridlock. Without confidence, and without jobs, people are not spending to help the recovery. Without spending, there’s no demand. Without demand, there’s no production and therefore no hiring. And you can complete that circle yourself.
 
As I’ve mentioned before, if we are headed for a recession, then stock prices will likely have to fall further before they are fairly priced. This is because earnings fall during a recession, and institutions only buy stocks when they’re fairly priced according to forward earnings. If we’re not headed for a recession, then stock prices are cheap and out to be bought hand over fist right here, right now. 
 
What we’ve witnessed in the stock markets over the past 8-9 weeks is extreme volatility brought on by the battle between those in the recession camp and those not in the recession camp (along with Eurozone worries).  Since the August 9th low in the markets, the S&P 500 has traded in a 100 point range and has basically gone nowhere.  This bouncing around will not continue forever (but can continue for months), and will give way to a big move up or down in the near future. The action during the past week tends to point to a downward move, but every downward move in this range looked like it was going to break down until buyers stepped in.
 
What I Believe and What We’re DoingAs evidence that points to a recession mounts, I’m becoming less convinced that we can avoid a recession in the next 3-6 months. This is a change from my previous stance of no impending recession in previous months. It’s become increasingly clear that the Federal Reserve is less able to influence what happens in the economy, and in my opinion, the less they do the better.
 
As the odds of a recession have been increasing, and world economies also slow, I have been slowly reducing client exposure to equities over the past couple of months. Our exposure to small cap stocks is now very small, and I began to reduce exposure to mid-cap stocks by up to 1/3 as of last week.
 
On Friday of this week, I increased our exposure to hedges via leveraged inverse exchange traded funds because I believe that we will test the August 9th low on the S&P 500 index of 1101 (current level of support) and may even break below it. I also believe that even if the market did decline by another 10% (should we break support) we still have a year-end rally in the cards.  Even if I’m wrong about reducing equity exposure and increasing our hedges, and the markets reverse and fly to the upside (not likely), prudent risk management based on the facts and circumstances warrant caution. It never hurts to reduce equity exposure when uncertainty and volatility rule the markets.
 
September 2011 was the 6th down month in a row in the stock markets, and bear markets typically last 6-18 months. If this is merely a correction and not a bear market, then 6 months is a good point in time to expect a bounce. My expectations, especially since this is the 3rd year of an election cycle, that somewhere along the lines of mid to late October, we begin to see the year-end bounce. 
 
As always, I offer my caveat: my crystal ball is in the shop and no one, including me, can forecast what the markets will do. I can only provide my best guess, and that’s what this is, a guess, based on all the information available to me and historical precedent, of what the markets may do. I could be totally wrong on both direction and timing, so no one should make any investment decisions based on my prognostications or forecast. Forewarned is forearmed.
 
I’m happy to answer any questions or comments you may have. If you already have a fee-only financial advisor (the only kind I recommend), then great. If you’re looking for an unbiased, fee-only financial advisor, don’t hesitate to contact us. Your first consultation is complimentary and comes with no pressure to act or sales tactics.  As fee-only fiduciary advisors, we act in your best interest and collect no commissions, trails or any hidden compensation.

Stock Market and Economic Update August 21, 2011

The past week hasn’t been particularly kind in the stock markets as we saw little follow-through on the previous week’s rally. My upside target of 1230-1260 in the S&P 500 index was not even approached before selling resumed at around 1208.
 
A few economic reports from last week have me a bit more concerned about the possibility of a recession within the next twelve months.  Although the economic leading indicators that I’ve come to rely on from the Economic Cycle Research Institute turned up again this past week, the only components to rise were financial ones, namely the money supply (with the stock market selling being a contributing factor) and the steep yield curve (ultralow interest rates on short duration debt versus higher rates on longer duration debt made possible by the Federal Reserve’s low interest rate policy). Without these two components, the index would have been down 0.5%, which is down three of the last four months.  Weekly unemployment claims came in at 408,000 whereas they were starting to trend below 400,000 in the last few weeks.
 
So the volatility in the market right now is at least partially attributable to concerns about whether a recession is on the horizon or not. If one is not, then the market is undervalued. If one is, then the market is overvalued. So far, the weight of evidence of a recession is still inconclusive, but it appears that institutional buyers are starting to “discount” that possibility as they demonstrate through selling in the markets.  The research I read is split about 50/50 about whether a recession is coming, with convincing cases made on both sides.  My feeling is that we have a bit further to go on the downside if economic factors or confidence measures don’t start pointing up real soon.
 
Accordingly, I am becoming increasingly concerned about the behavior of the markets and the economic numbers coming out lately since they haven’t been particularly encouraging. Accordingly, this past week I increased my clients’ hedges and continued to slightly reduce exposure to equities just to be on the safe side. 
 
This week will be critical since the Federal Reserve Chairman (Ben Bernanke) will be speaking on Friday and will reveal any further measures they may take to ease recession concerns and restore confidence to the markets.  More information about how the Eurozone will handle its debt crisis should help calm the markets.  But based on the market action on Thursday and Friday, it seems that many institutional and retail investors are not waiting to hear what the Chairman has to say or what solution the Eurozone might propose to avoid a deepening debt crisis.  They have therefore been selling and may continue doing so into this week.
 
I will continue to monitor the markets day to day and make further adjustments to portfolios and increase hedges as conditions warrant. Since the market is heavily oversold, we should expect some level of a bounce this week, if only for folks to prepare for any surprise announcement the Federal Reserve Chairman might offer to help propel markets higher.

Bottom line, it’s too early to reach conclusions about whether or not the April high was an important top in the market. If it was, it was unlike any market top of the past 50 years, with both the LEI and market breadth still hitting new highs after the top. When panic selling spreads across the board – good quality companies go down along with the overvalued speculative stocks.  I can say that barring some type of financial Armageddon, I believe the downside valuation risk in this market is far less than in 2007-08. 

My major equity allocation decision is to give this market more time before making any major adjustments. What is needed –more than anything else– is stability and confidence. Only time and stability can calm the emotional extremes and fears, which still come out of the woodwork on a daily basis. But as I’ve said, if the retest (of the S&P 500 index lows of 1100) is able to hold above the lows of last week, then it could provide a strong market base if evidence of a recession does not increase in coming weeks.

Again, please do not take this message as advice to buy or sell any securities; please consult with your investment advisor (or us!) This message is not intended to forecast what will happen in the market since no one (including me) can do that. My objective is to share what I’ve been hearing, reading and researching, the end result of which is one of cautious optimism.
 
Please don’t hesitate to contact me if you need any help with your personal financial situation or investments.  I welcome your feedback and questions always.

Why I Don’t Trust This Rally

We finally strung together three up days in a row in the stock markets today and that’s a good thing. Volatility is ratcheting down and folks are stepping in to scoop up bargains.  Unfortunately, for the first time since we bottomed back in March 2009, I don’t trust this rally and believe that we are headed back to test last week’s low of 1,101 on the S&P 500 index in the short term.  If the market doesn’t hold at that level, our next stop is likely 1060. Let me explain why this rally has a lot to prove before I believe that this correction is over:
 
1.  Other than relieving an oversold condition, not much has changed fundamentally between last week and today. Uncertainties are abound about the possibility of a recession starting or already started (which I don’t believe), how we’re going to deal with raging federal deficits, and the Eurozone debt crisis. A meeting between German and French officials tomorrow will shed some light on how they will deal with the debt crisis in Europe.
2.  The three day rally that began last Thursday has occurred on light volume, reflecting very little institutional participation.  Institutions often wait for retail investors to bid up the market after a severe selloff to set it up for more selling.  The selling has been coming in on very heavy volume while buying is coming in on light volume, a bearish sign.
3.  Consumer confidence, as measured by the University of Michigan survey released last Friday, was at a record low.  These levels have not been seen since the great recession (but do reflect the recent anxiety over the recent U.S. debt ceiling debacle and stock market sell-off last week).
4.  The main stock market sentiment indicators showed an increase in bullish sentiment last week. This is considered a “contra” indicator. After the recent stock market beating, there seems to be more complacency than fear in the markets. Folks are still in “buy the dip” mode. They might have buyer’s remorse if they’re short-term holders.
5.  The kind of technical damage to the markets caused by last week’s sell-off takes weeks, if not months, to repair.  After-shocks and re-tests of lows are the norm after such a severe sell-off.
The positives that point to a better economic environment and stock market include a better than expected weekly jobs report last week, improved July retail sales figures, good corporate insider buying, and more big corporate mergers announced today.
 
While I believe that the markets could bounce for a few more days, unfortunately, I feel that we are headed lower over the short-term. The S&P 500 index closed at 1204 today, and we may even climb as high as 1240-1260 before the markets “roll over”.  That is 3-4% from here, and it’s only an educated guess on my part since 1250 is approximately where the markets fell apart.  I’d like to take advantage of this short-term rise, but only if more volume confirms the move higher.  Otherwise, it’s easy to get whip-sawed in this low volume environment. 
 
This is why I continue to hold onto hedges and have refrained from putting available cash to work at this point.  I’ve continued to selectively cull positions and rebalance accounts to take advantage of the recent strength in the market. Nonetheless, we remain heavily weighted long in the equity and bond markets despite our cash and hedges.  If the S&P 500 index closes above 1290 convincingly, then I’ll re-evaluate my stance, consider pulling in my hedges and invest more cash.
 
But aren’t we investing for the long term? Why should short-term market dynamics control our investing decisions? While we do invest for the long term, it’s prudent to protect capital when the market is in a well-defined downtrend, especially when a near-term recession is a possibility, albeit a remote one.  Markets around the world are factoring in a global slowdown, and the U.S. won’t be immune.  Sure central banks may pull a rabbit out of their hat and stimulate the economy and markets once again, and I’ll be ready for that.  But for right now, unless I see some institutional “power” behind this rally, I just don’t trust it.  As I’ve mentioned before, I expect near-term market weakness until sometime in October.
 
No part of this message should be considered a recommendation to buy or sell any securities, and you should not act on this without consultation with your financial planner or money manager (better yet, talk to us!)  My position will change if the facts change, so I am not married to this position. That could be tomorrow, next week or next month. I don’t have a crystal ball, so my prognostication should not be taken as true fact (I could change my mind or worse, be wrong!)
 
Please let me know if you have any questions, concerns or feedback. I’d love to hear what you’re thinking.